DeFi staking sits at the intersection of blockchain security, onchain yield, and programmable finance. At a basic level, staking means committing crypto assets to help support a network or protocol in exchange for rewards. On Ethereum, staking is tied directly to proof-of-stake: validators stake ETH to help verify blocks and secure the network. Ethereum’s official documentation explains that validators explicitly stake ETH into a smart contract and can earn rewards for honest participation, while also facing penalties if they behave improperly or fail to perform their duties.
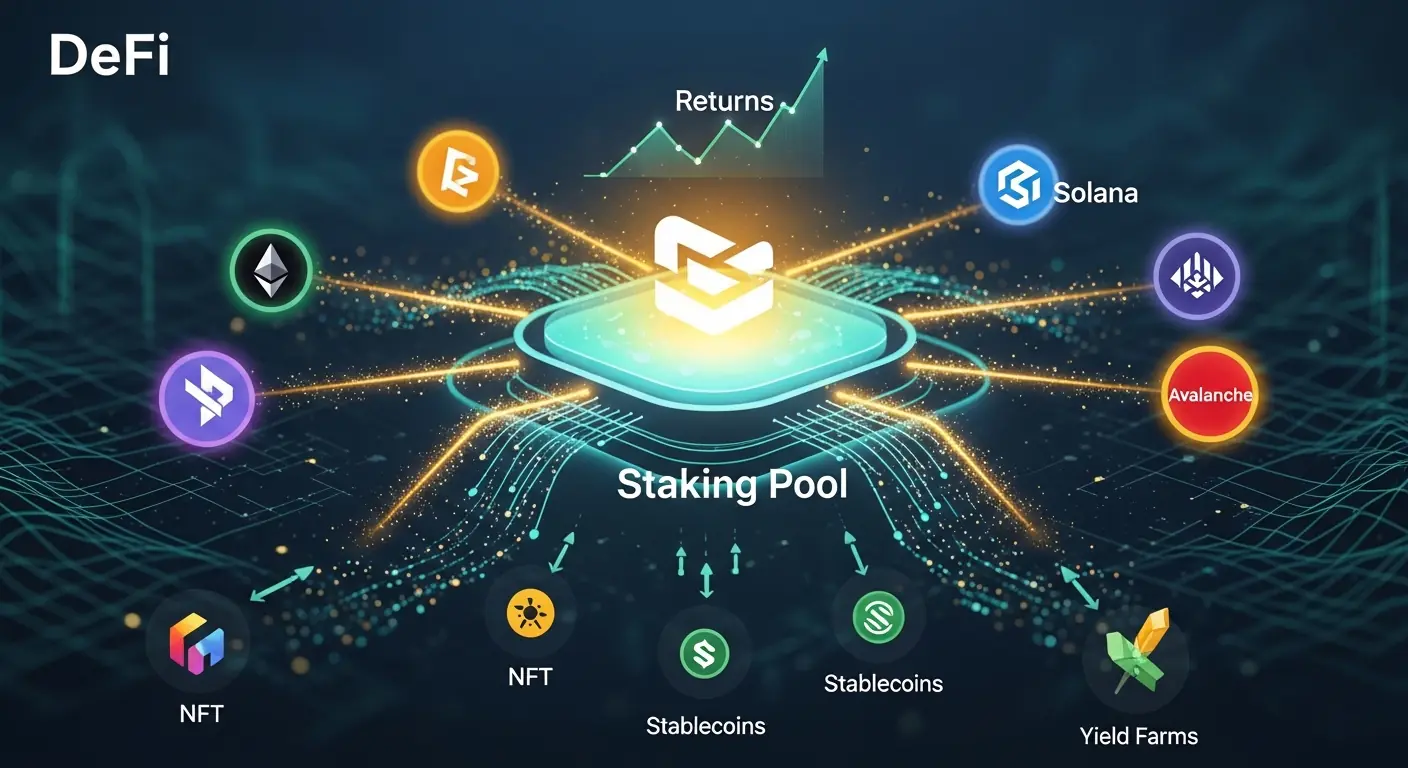
In decentralized finance, staking has expanded beyond the narrow idea of running validators. Today, DeFi staking can refer to several related models: staking native tokens to secure a proof-of-stake network, depositing assets into liquid staking protocols that issue a liquid receipt token, or staking protocol assets into backstop or security modules that help absorb risk while earning incentives. This broader meaning is why DeFi staking matters so much. It is no longer just an infrastructure activity for technically skilled validators. It has become a flexible yield and participation layer for a much wider set of users.
The market importance of this segment is easy to see. CoinGecko’s Q3 2025 industry report said DeFi total value locked rose from $115 billion to $162 billion during that quarter, showing a broad recovery in onchain finance. At the same time, CoinGecko’s Q1 2025 report noted that liquid staking and restaking protocols were among the largest categories in DeFi even during periods of outflows and repricing. In other words, staking has remained a core part of DeFi through both expansion and contraction.
What DeFi staking actually means
The first thing to understand is that DeFi staking is not one single mechanism. In its simplest form, staking means locking or delegating assets so they can contribute to consensus or protocol security. On Ethereum, solo staking requires 32 ETH to activate validator software. Ethereum.org also explains that pooled staking allows smaller holders to participate without meeting the 32 ETH threshold themselves. That lower barrier to entry is one of the reasons staking moved into mainstream DeFi usage.
From there, DeFi created additional layers. Liquid staking protocols let users deposit ETH and receive a tokenized representation of their staked position. Lido says users can stake their tokens while keeping them liquid for use across DeFi applications, and Rocket Pool similarly describes liquid staking as receiving a receipt token that continues to earn rewards while remaining transferable. This model is important because it solves one of staking’s oldest tradeoffs: earning yield traditionally meant giving up liquidity. Liquid staking reduces that tradeoff by turning a staked position into a usable onchain asset.
There is also protocol staking, which is structurally different from validator staking. Aave’s Safety Module, now upgraded into Umbrella, allows users to stake certain assets to help protect the protocol against shortfall events. In exchange, participants earn incentives, but their assets may be slashed if the protocol needs to cover losses. This shows that in DeFi, staking can mean security provisioning for an application rather than consensus participation for a blockchain.
How the mechanics work
The mechanics depend on the staking model, but the logic usually follows a consistent pattern. A user deposits an asset into a smart contract. The protocol then either delegates that capital into validator operations, pools it with other deposits, or holds it as a risk buffer. Rewards are distributed based on protocol rules, and in some systems users receive a derivative token that represents their claim on the underlying staked position.
In Ethereum-native staking, the mechanism is tightly linked to proof-of-stake. Validators propose and attest to blocks, and rewards come from participation in consensus. Ethereum.org notes that staking strengthens network security by requiring validators to put capital at risk. If they act dishonestly or fail operationally, they can face penalties. This economic design is central to why staking works: it aligns financial incentives with honest network behavior.
In liquid staking, the process adds another layer. Lido’s contract documentation explains that the core contract accepts user deposits, buffers them, mints corresponding liquid tokens, collects withdrawals and fees, and distributes rewards based on protocol accounting. That means the user is no longer interacting only with the base staking layer. They are also relying on smart contract architecture, accounting logic, oracle reporting, and withdrawal systems. The convenience is real, but so is the added complexity.
In protocol security staking, the mechanics are even more application-specific. Aave explains that users stake aTokens, GHO, or other supported assets into Umbrella to provide an additional protection layer for Aave v3 pools. Users earn incentives for taking that risk, but the position may be slashed in the event of a shortfall. This is less about consensus and more about onchain risk mutualization.
This layered design is why DeFi Staking Platform Development is more involved than simply creating a deposit contract. A serious staking product has to manage validator economics, token accounting, smart contract security, withdrawal logic, reward distribution, user experience, and risk controls in one coherent system. The mechanism has to work not just in ideal conditions, but under stress, volatility, and adversarial behavior.
Why users stake in DeFi
The most obvious reason is yield. Staking lets users earn rewards on assets they would otherwise hold passively. Ethereum describes staking as a way to earn ETH while helping secure the network. Liquid staking protocols extend that benefit by letting users continue to deploy the staked representation elsewhere in DeFi. In practice, that means a user may earn base staking rewards and also use the liquid token in lending, trading, or collateral strategies.
The second reason is accessibility. Ethereum.org states that pooled staking significantly lowers the barrier to entry because users can stake small amounts, do not need validator keys, and do not need specialized hardware. That is one of the biggest reasons DeFi staking grew so quickly. It converted staking from a technically demanding infrastructure role into a consumer-grade financial action.
The third reason is capital efficiency. Traditional staking ties up assets. Liquid staking created a more efficient model by issuing transferable tokens against the staked position. Lido explicitly highlights this as a core advantage: users keep liquidity and can use the token across DeFi while still earning staking rewards. This makes staking much more attractive to active market participants who do not want their capital trapped in a single utility.
The current scale of that demand is visible in market data. On March 30, 2026, DefiLlama listed one major liquid staking pool with about $18.239 billion in TVL and a roughly 2.38% APY, while another tracked liquid staking pool showed around $2.721 billion in TVL with a roughly 2.09% APY. Those figures move over time, but they illustrate how much capital sits in liquid staking products and how modest but persistent the yield profile can be in mature markets.
The main benefits of DeFi staking
One major benefit is predictable onchain income. Staking rewards are not guaranteed, but they are usually governed by transparent protocol rules rather than opaque discretionary decisions. That makes staking attractive to users who want systematic crypto-native yield rather than purely speculative upside. Ethereum, Lido, and Aave all present staking as a structured reward mechanism tied to specific responsibilities or risk assumptions.
Another benefit is network and protocol alignment. Stakers are not just passive investors. They often become stakeholders in the health of the system. In Ethereum staking, this means helping secure the chain. In Aave’s protection model, it means helping strengthen the protocol’s resilience. This alignment is important because DeFi works best when the people earning rewards are also supporting system stability.
A third benefit is composability. Liquid staking tokens can move across DeFi applications. That makes them useful as collateral, trading inventory, or yield-bearing building blocks. It is one of the clearest examples of how DeFi turns a single financial position into a reusable primitive. A staked asset is no longer just locked collateral. It becomes a programmable object that can interact with other protocols.
The risks users should not ignore
DeFi staking is attractive, but it is not risk-free. The first risk is slashing or penalty risk. Ethereum’s proof-of-stake model can penalize validators for dishonest or faulty behavior, and protocol-level staking systems like Aave can explicitly slash assets to cover shortfalls. If users do not understand what backs their rewards, they may misunderstand the real risk they are taking.
The second risk is smart contract risk. Liquid staking and protocol staking add code layers on top of the underlying asset. A flaw in deposit logic, reward accounting, withdrawal design, or access control can create losses even if the underlying blockchain remains secure. Lido’s own documentation shows just how many moving parts exist in a major staking protocol, from buffering and minting to oracle reports and withdrawal queues. More moving parts usually mean more attack surface.
The third risk is liquidity and pricing risk. A liquid staking token is designed to represent staked value, but its market price can diverge from the base asset in periods of stress. The token may remain useful, but users should not assume perfect one-to-one liquidity under all market conditions. The practical benefit of liquid staking is strong, but it depends on secondary-market depth and redemption mechanisms continuing to function well. That is why protocol design and market structure matter as much as headline APY.
There is also concentration risk. If too much staking power or liquid staking market share gathers around a small number of providers, decentralization concerns increase. Ethereum.org notes that home staking contributes more directly to decentralization and censorship resistance than some other options. That does not mean pooled or liquid staking is bad. It means convenience has system-level tradeoffs.
Because of these layers, many teams now work with a defi staking platform development company when they want to launch staking products that are technically credible and commercially viable. A platform has to balance user simplicity with validator economics, contract safety, liquidity design, and governance discipline. That is not trivial engineering.
Real-world use cases
The clearest use case is Ethereum liquid staking. A user deposits ETH into a protocol such as Lido or Rocket Pool, receives a liquid token, earns staking rewards, and can still use that token within DeFi. This model is especially useful for users who want exposure to Ethereum staking without operating validators or meeting the 32 ETH requirement.
A second use case is protocol backstopping. Aave’s Umbrella system shows how staking can be used to support solvency and automated bad-debt protection. In this case, staking is less about passive yield and more about contributing to a shared safety layer for a financial protocol. That expands the role of staking from network consensus into risk infrastructure.
A third use case is portfolio efficiency. A liquid staking token can be held, transferred, used as collateral, or integrated into broader DeFi strategies. This turns staking into a building block for treasury management, structured products, and advanced onchain strategies. It is one reason staking is now seen as a foundational DeFi primitive rather than a narrow niche activity.
That opportunity is also why some projects position themselves as a defi staking development company rather than merely a smart contract vendor. The market increasingly expects full-stack staking systems: validator integration, liquid token logic, withdrawal management, security review, and usable front-end flows. Users are not just looking for yield anymore. They want reliability, transparency, and flexibility.
Conclusion
DeFi staking works by turning crypto assets into productive onchain capital. Sometimes that capital secures a proof-of-stake network. Sometimes it powers liquid staking systems that preserve usability. Sometimes it supports a protocol’s own risk and protection layer. Across these models, the core idea stays the same: users commit assets, protocols define the rules, and rewards flow in return for security, liquidity sacrifice, or risk assumption.
Its appeal comes from yield, accessibility, and composability. Its risks come from slashing, smart contracts, market structure, and concentration. That balance is what makes DeFi staking so important. It is not just a passive income tool. It is a mechanism that helps hold together many of the most important parts of modern onchain finance. When designed well, it improves capital efficiency and network participation. When designed poorly, it can expose users to risks they do not fully understand. That is why learning the mechanics behind DeFi staking is essential for anyone serious about blockchain finance.